FlexiFin

1 | ABOUT THE PROJECT
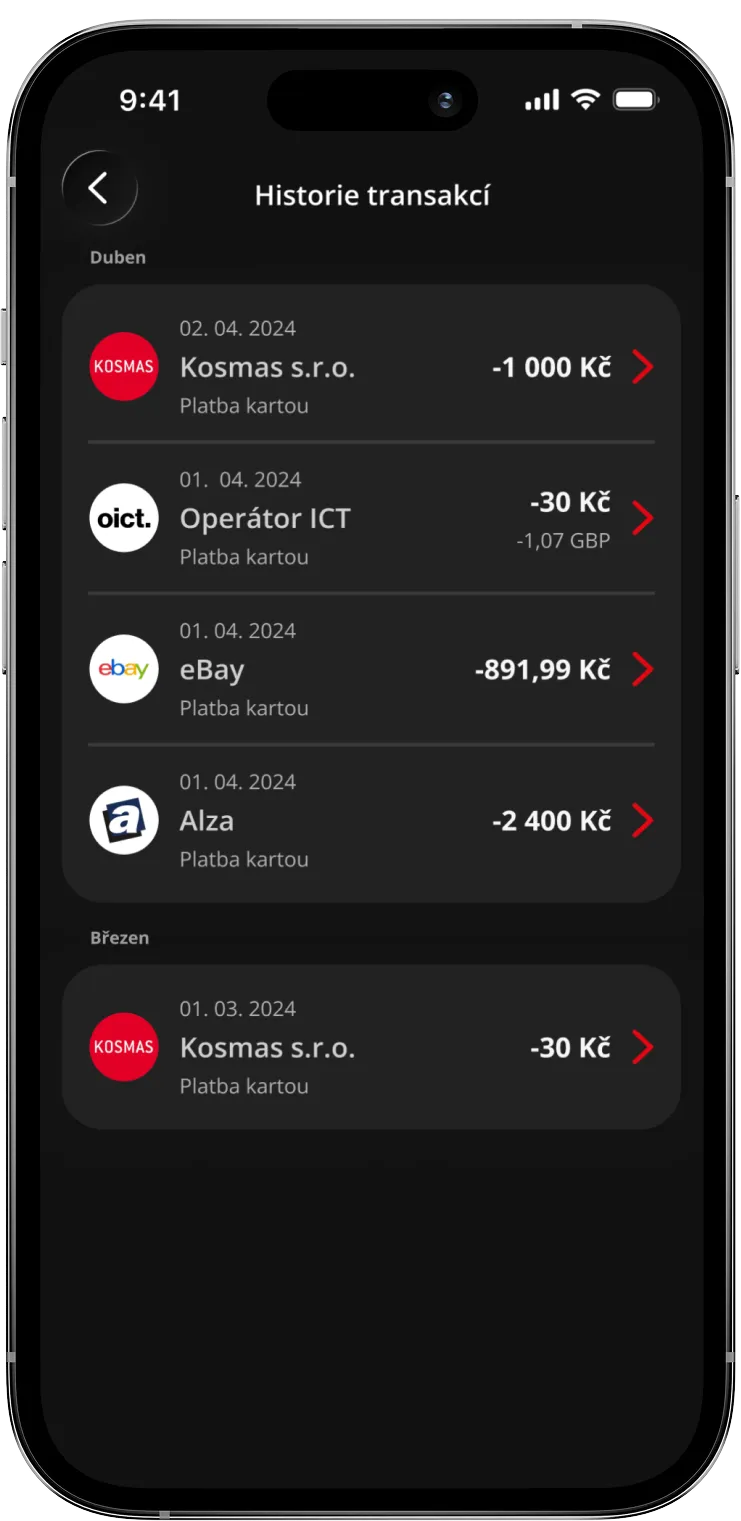
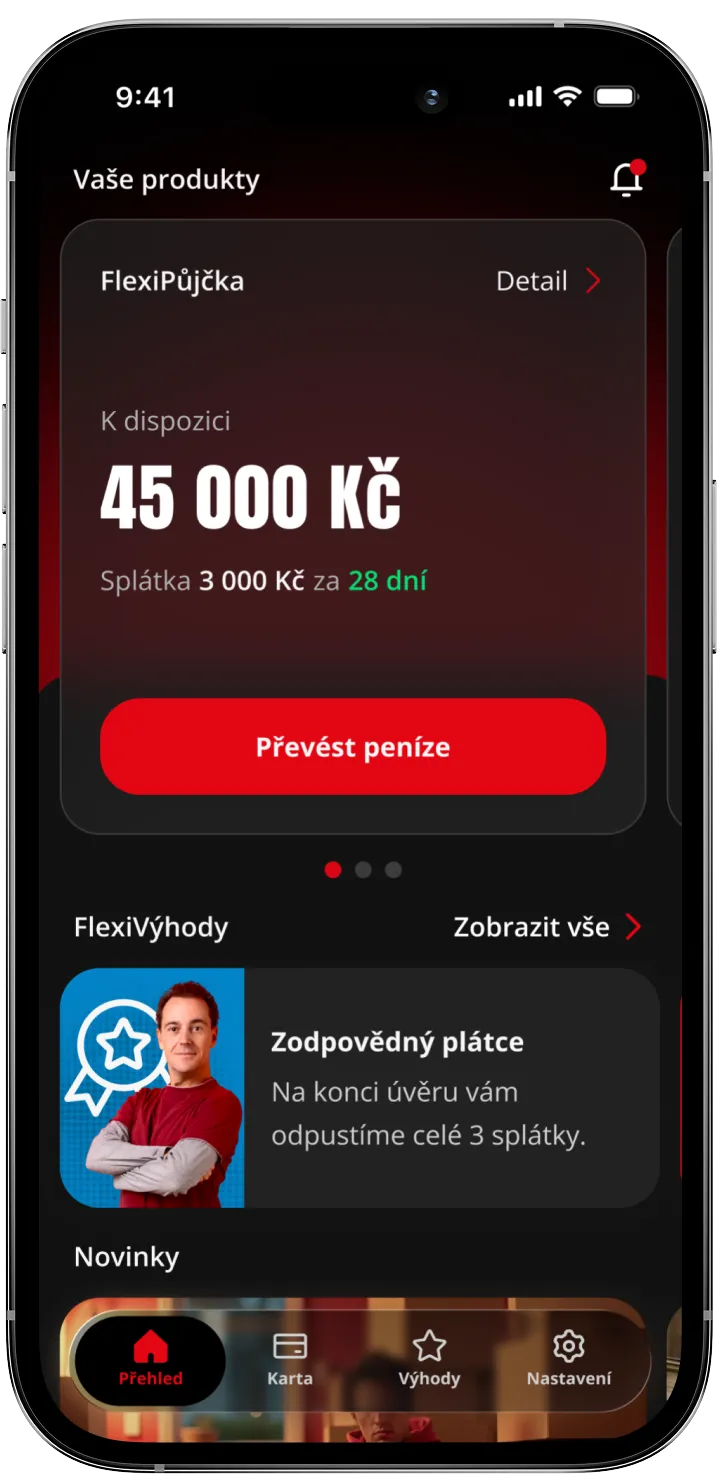
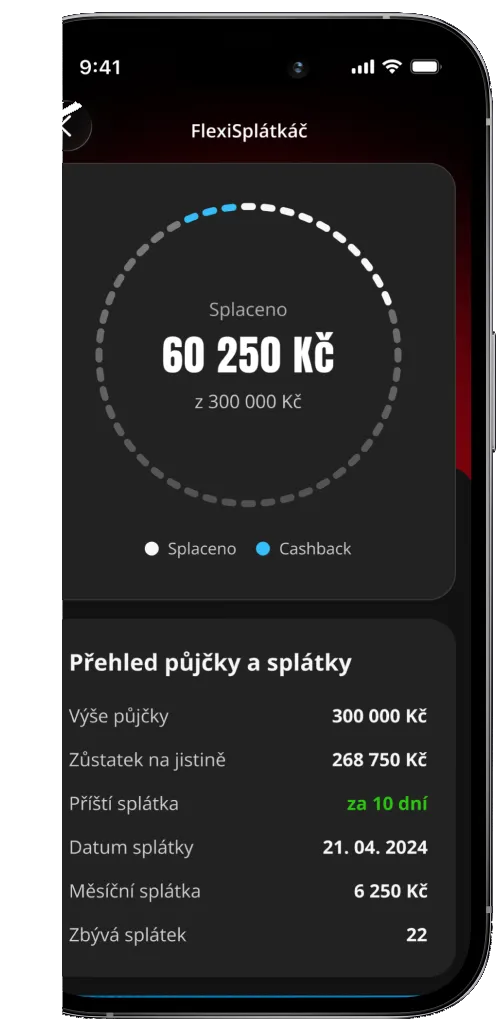
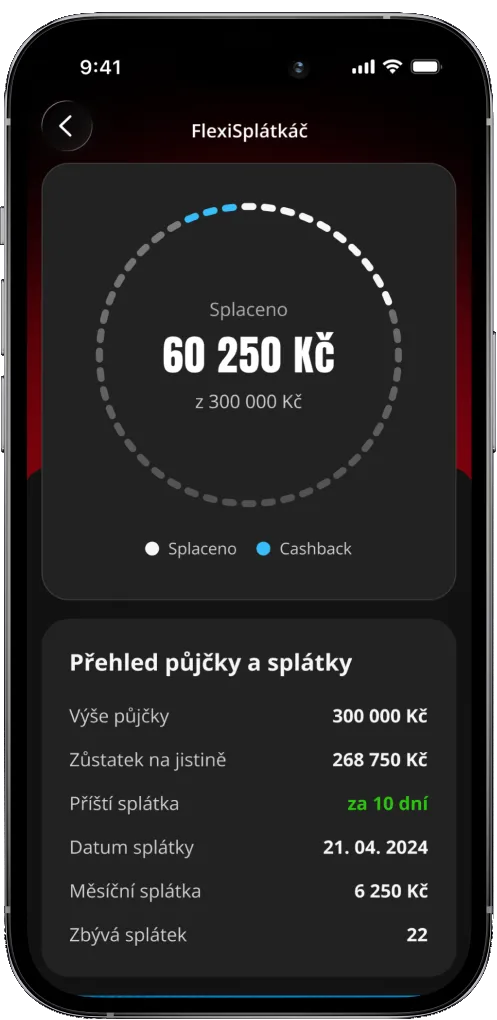
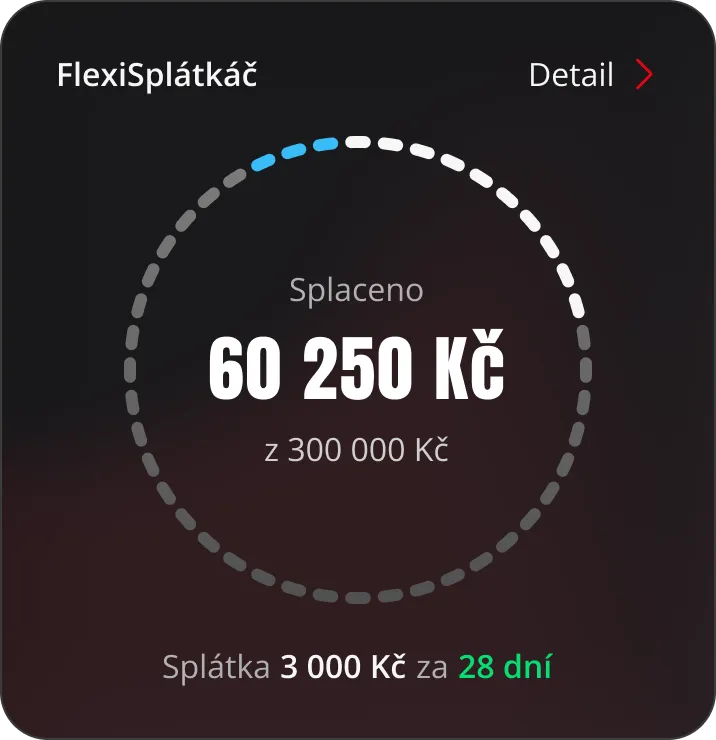
A mobile app for managing and tracking loans. In roughly a year, it became the service's primary transaction channel – today more than 80% of all client transactions run through it. The website, which the app once merely complemented, has now become the complement itself.
SERVICES
TECHNOLOGIES
80% +
Of transactions via the mobile app
2-3x
More app interactions than via the web
1 year
Before the app became the main transaction channel
99.5%
App crash-free rate
2 | CHALLENGE
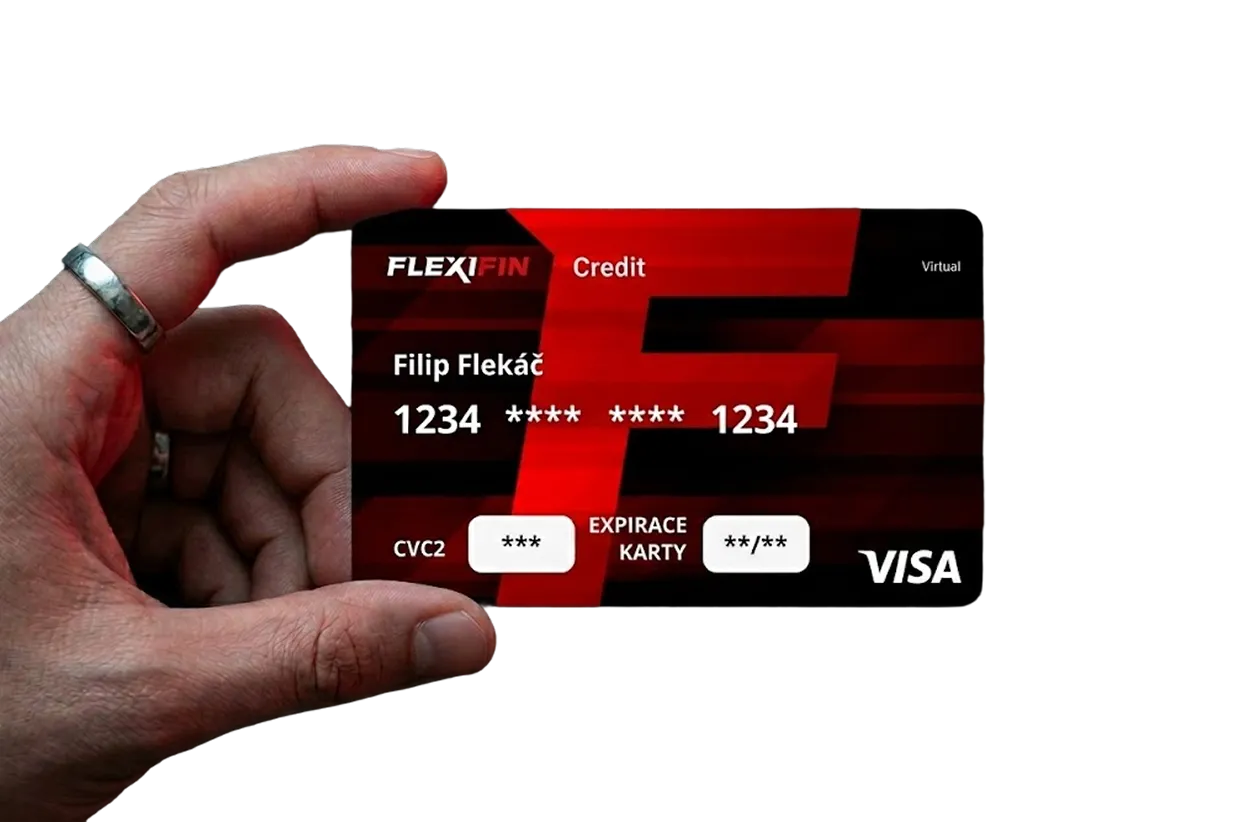
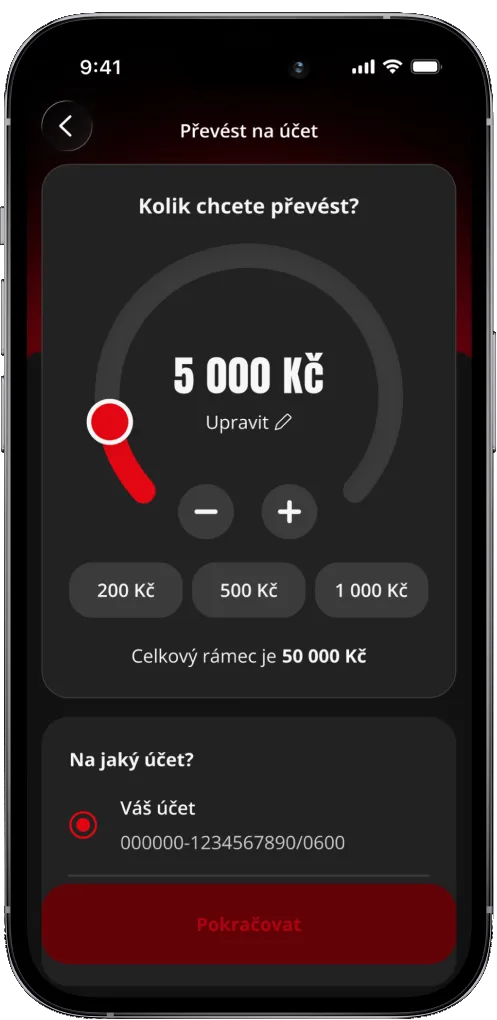
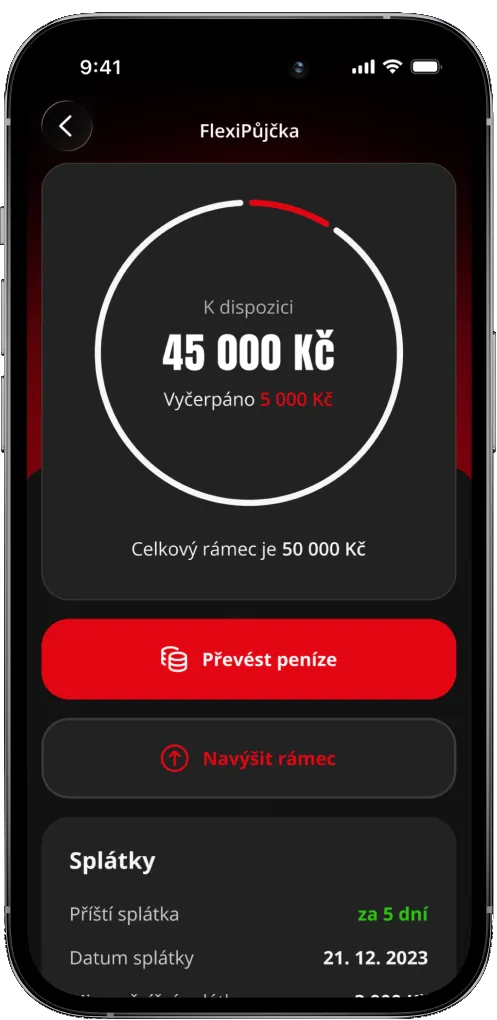
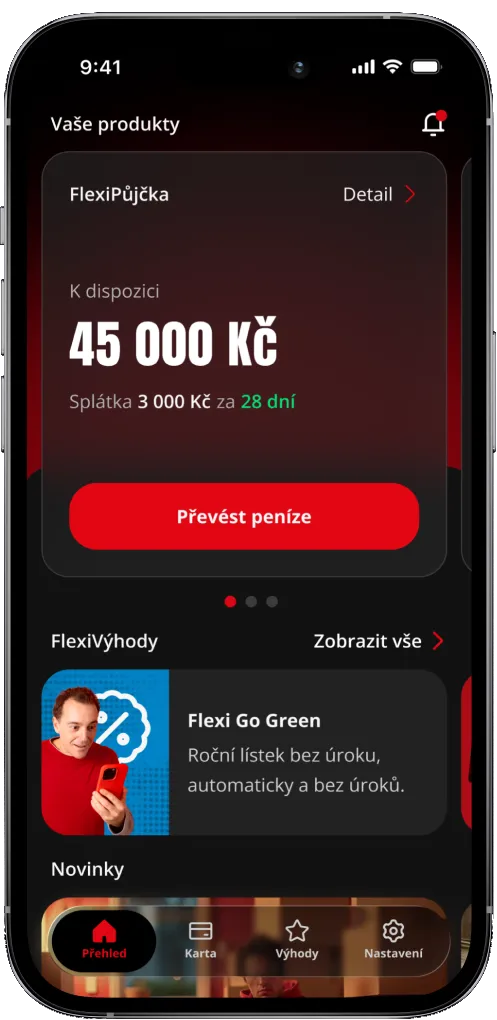
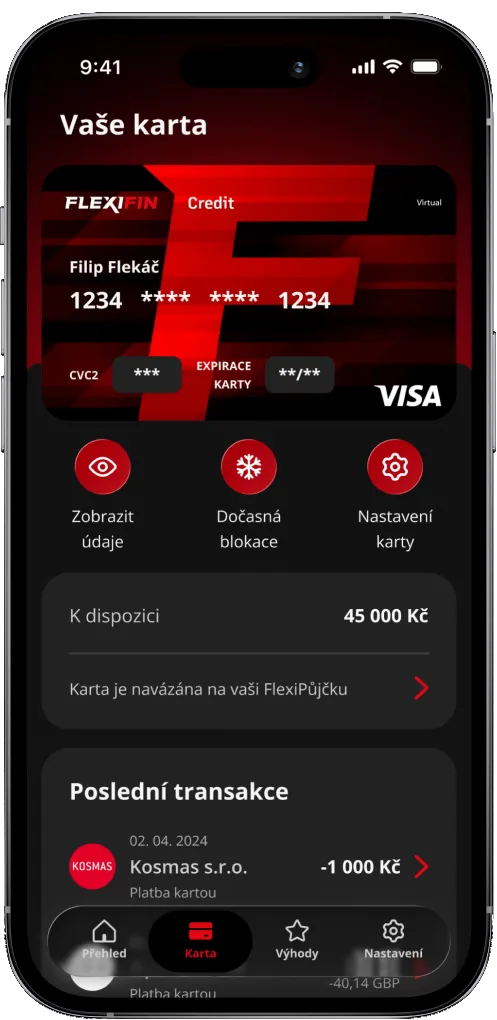
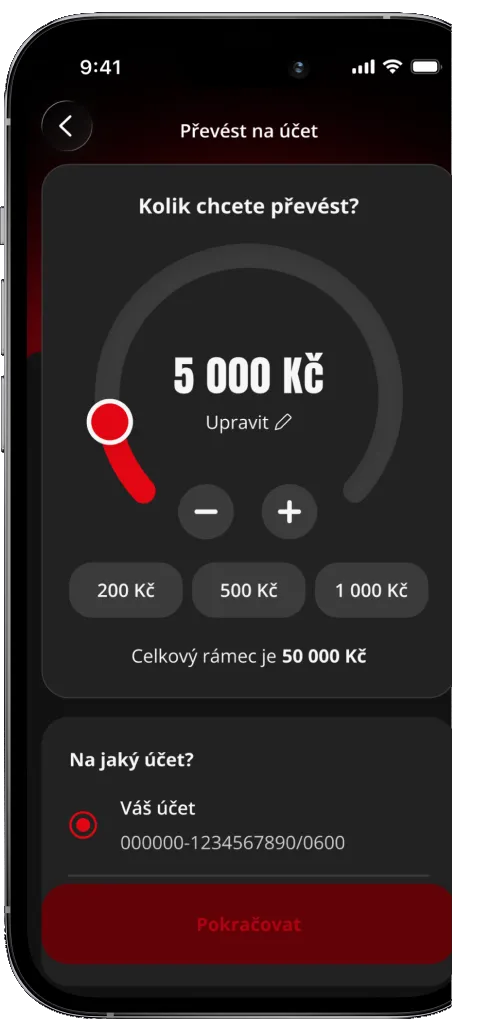
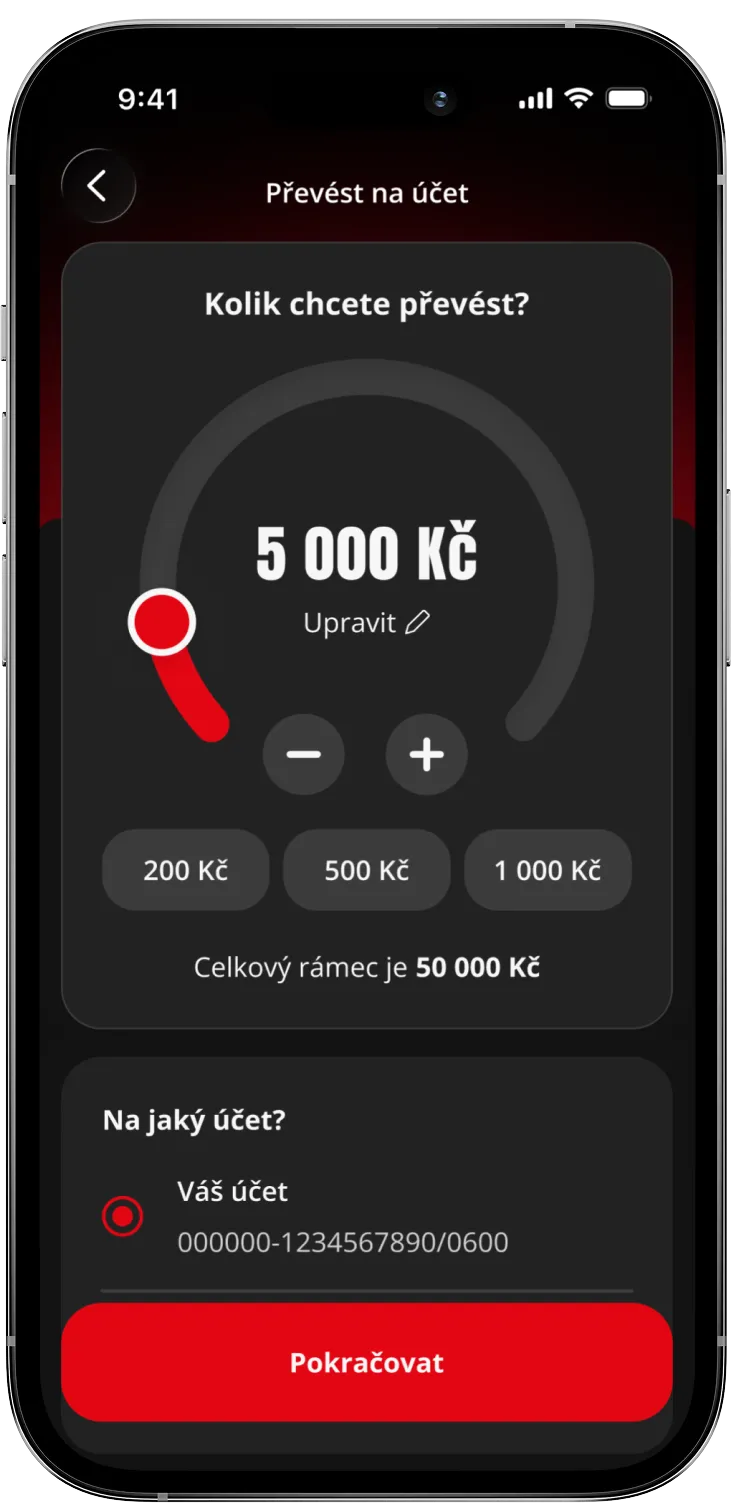
FlexiFin already had a working web interface where clients managed their loans. The app therefore couldn’t be just a smaller version of it. It had to add something extra: faster access to money, a real-time overview, and features the web can’t handle. A payment card right there in the phone, for example.
WHAT WE MEASURED
Push notifications beat email
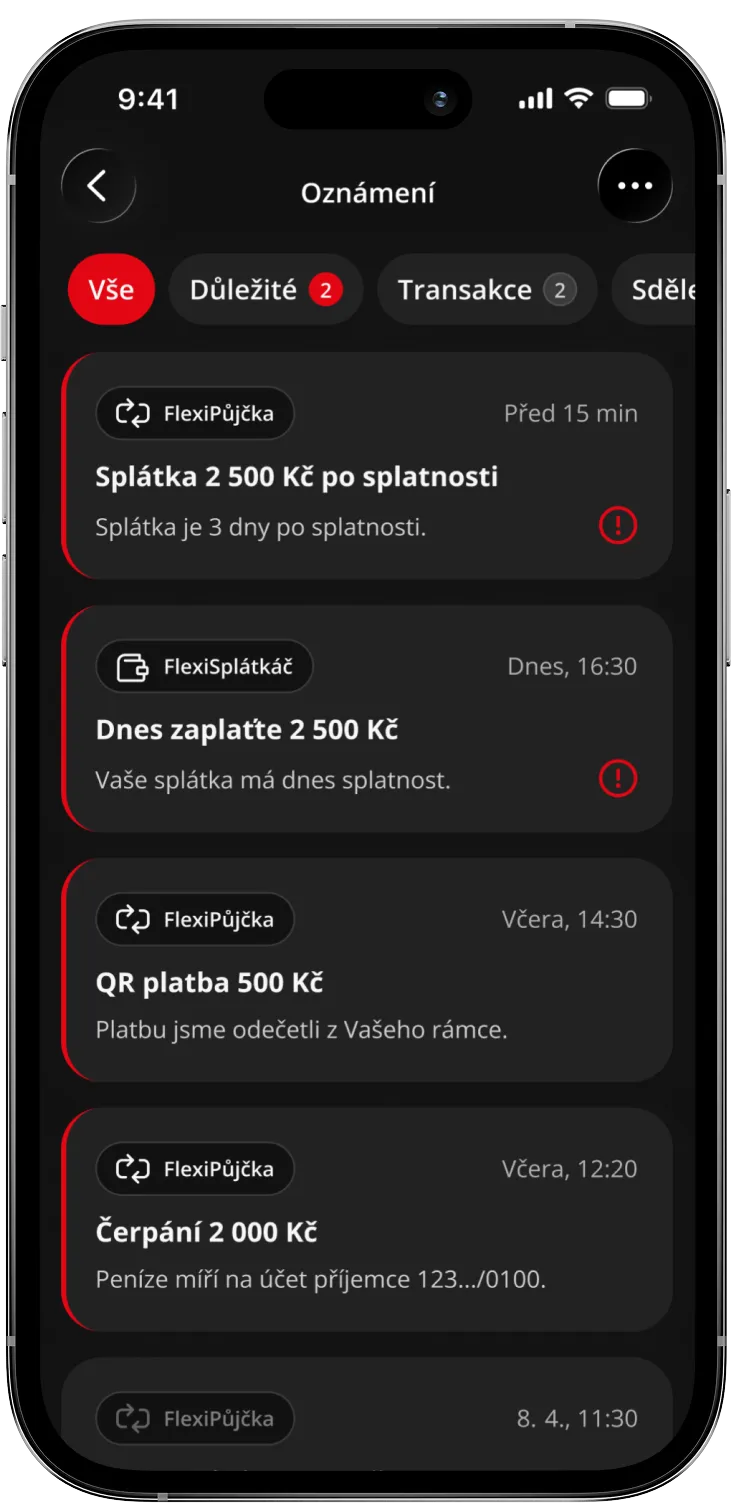
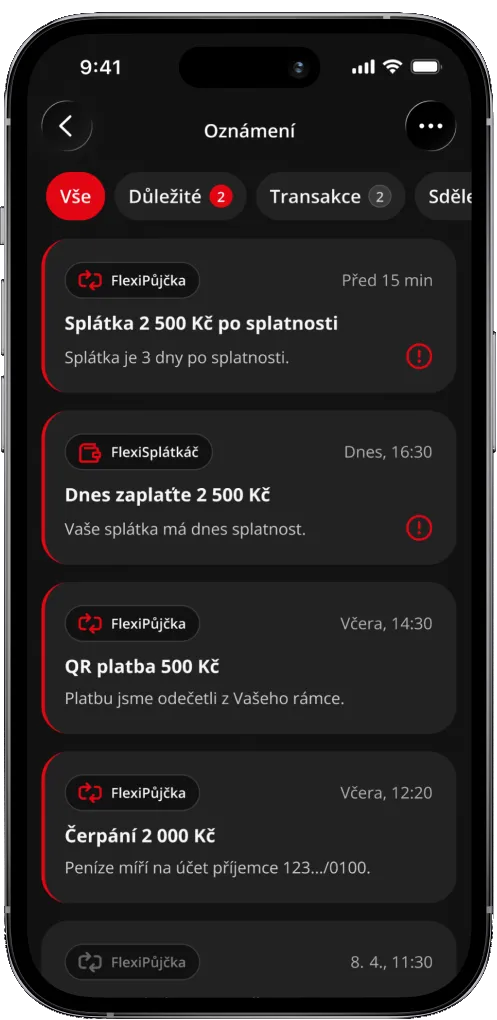
With personalised push notifications, clients started responding to instalments and offers noticeably more than via email.
2-3×
Higher notification CTR
3 | SOLUTION
We opened the project with a twelve-week product discovery: user interviews, usability testing, iterative design. Until then, FlexiFin had never done its own user research. That experience is what we brought to the project.
01
Discovery first
12 weeks of research and usability testing before a single line of code was written. Both teams pulled in the same direction.
02
Continuous discovery & delivery
Continuous feedback let us catch dead ends before anything cost money.
03
A partner, not a vendor
We go beyond the scope of our contract. We feel responsible for the whole, not just our own patch.
“
An extended team, not just a vendor
“From the very start I liked that you looked at what our customers would get out of it – not just at the brief. On top of that, speed and willingness: you have never turned me down, you always try to help. It works more like you’re our extended team than a vendor. And that happens with very few partners.”
Milan Dolanský | CMO
4 | Payment cards
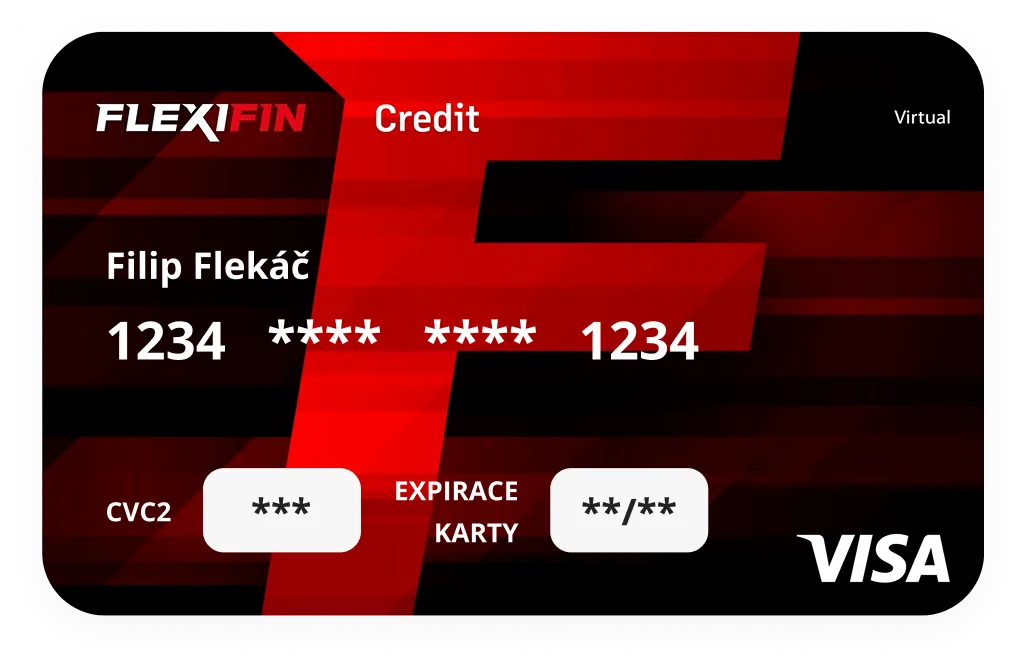
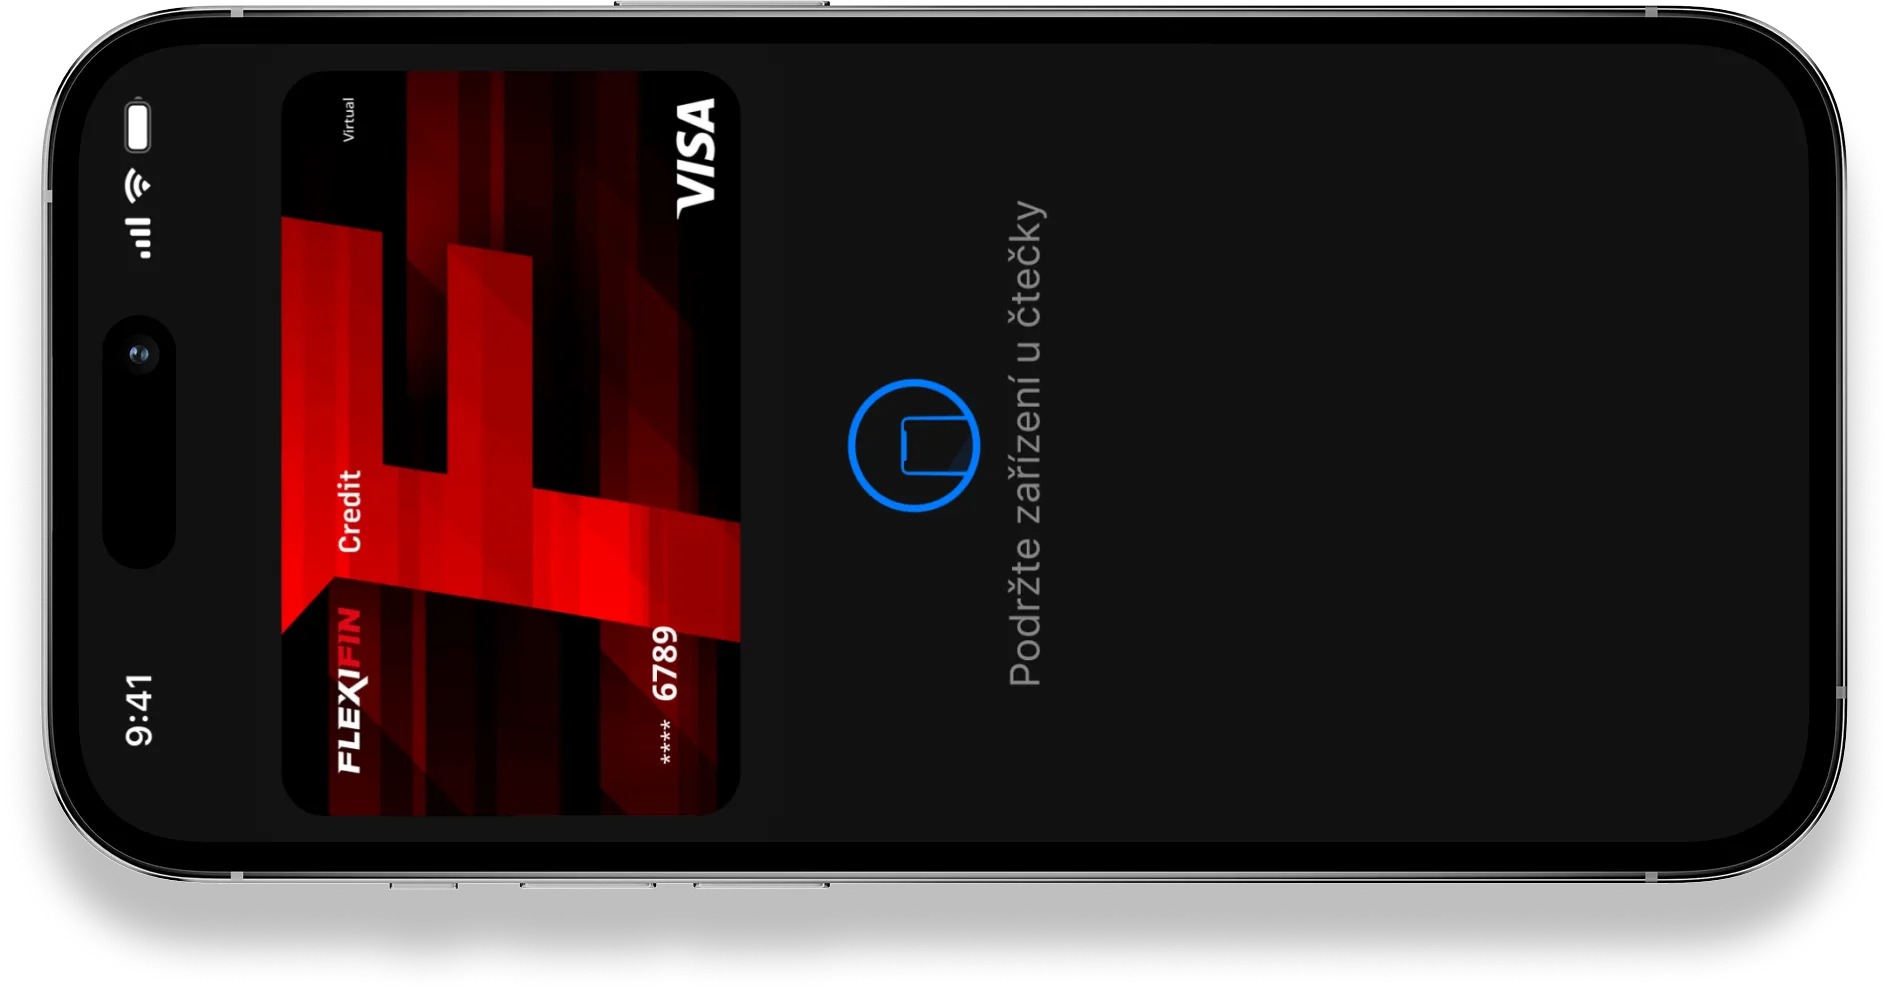
At first, the FlexiFin card was effectively virtual only. You could pay with it online, but in a shop it was useless. Once it was added to Apple Wallet and Google Wallet, clients pay with FlexiFin everywhere, by phone or watch, just like with an ordinary bank card.
The most technically demanding part of the project. We had to meet the requirements of Visa, Apple and the card provider all at once, and cover hundreds of scenarios where the card lives outside the app: in the wallet, on a watch, during a block or an incoming call. Designing the screens was the least of it.

600+
Scenarios covered for Apple certification

2 months
From kick-off to store release

Certification
We managed both the Apple and Google Wallet certification for the app
CHRISTMAS CAMPAIGN
The lowest acquisition cost ever
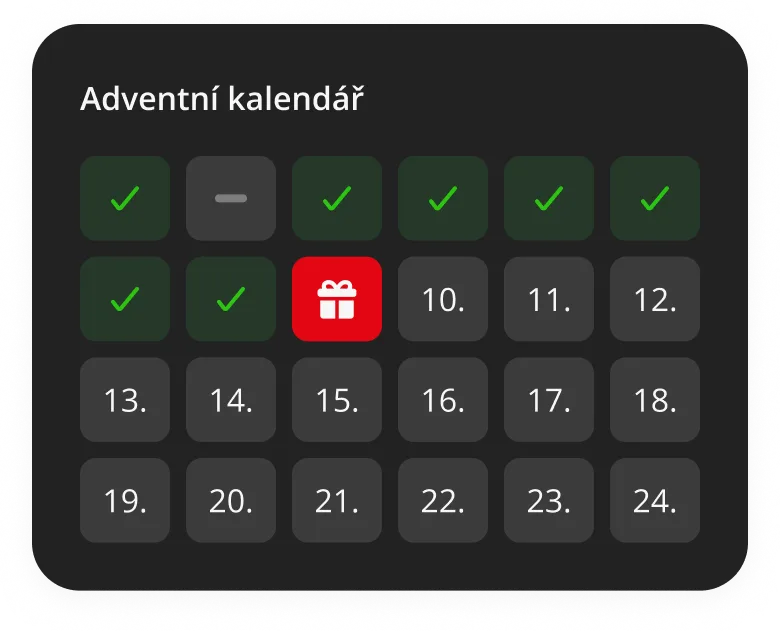
The Christmas game runs for roughly 24 days each year, with something new every day. Acquiring a client through it costs the least we have ever seen: it pulls in people who weren’t opening the app before, and the daily habit keeps them there afterwards.
5 | The main channel
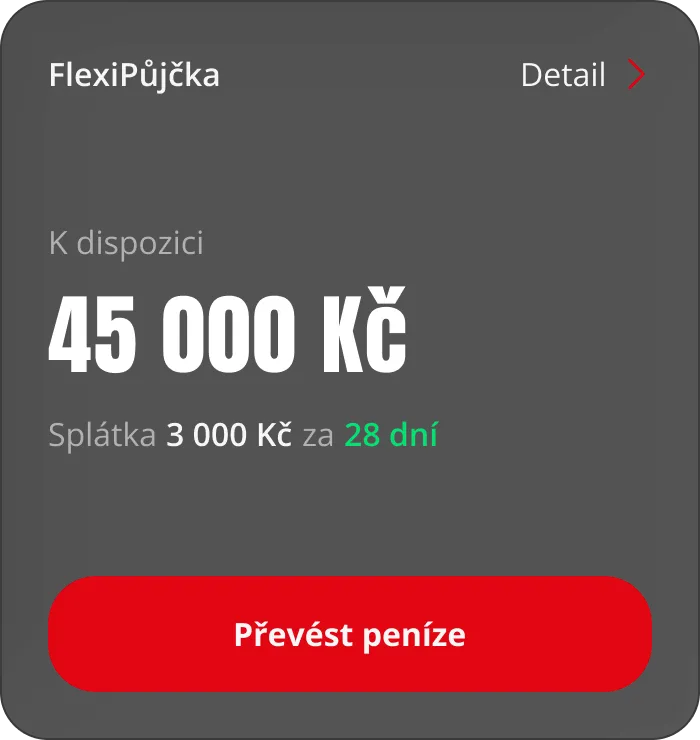
From the outset we built the app as the main channel. For a long time, though, it dragged. The app was an add-on and clients had no reason to leave the web they were used to. Saying “we have an app” wasn’t enough – on its own, people simply didn’t care.
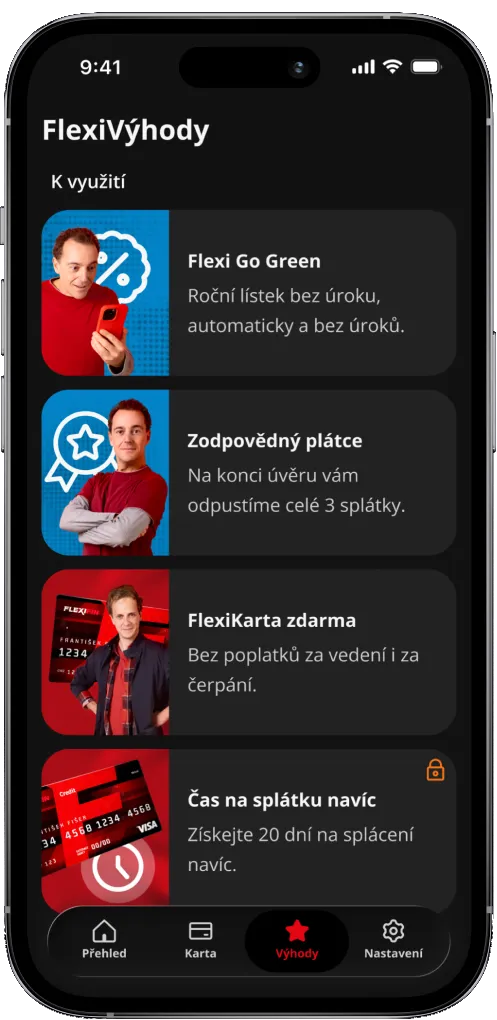
The turning point came when we gave clients a small advantage in the app. A discount worth a few crowns, and some features moved to mobile only. If you wanted them, you had to go into the app. We gradually flipped the messaging: we stopped saying “we have an app” and started saying “this only works in the app”. The app gives you something extra; the web is just the basics.
6 | Communication and retention
Unlike the web, which waits for the client to come along, an app can reach out on its own. Clients do read push notifications and opt into them more readily than we expected. They have to be handled with care, though: the moment a company treats notifications as just another advertising space, it loses the permission to send them.
So we handle notifications carefully: personalised, usually with a deep link straight to the place where the client needs to do something, and above all with a clear benefit. A repayment reminder or a payment authorisation is something the client wants. A blanket marketing message isn't. The result is more frequent but welcome interaction: clients come back to the app on their own, and the FlexiFin brand stays in front of them on their phone's home screen.